LAB-002 / Data + software
Aurora Market Intelligence.
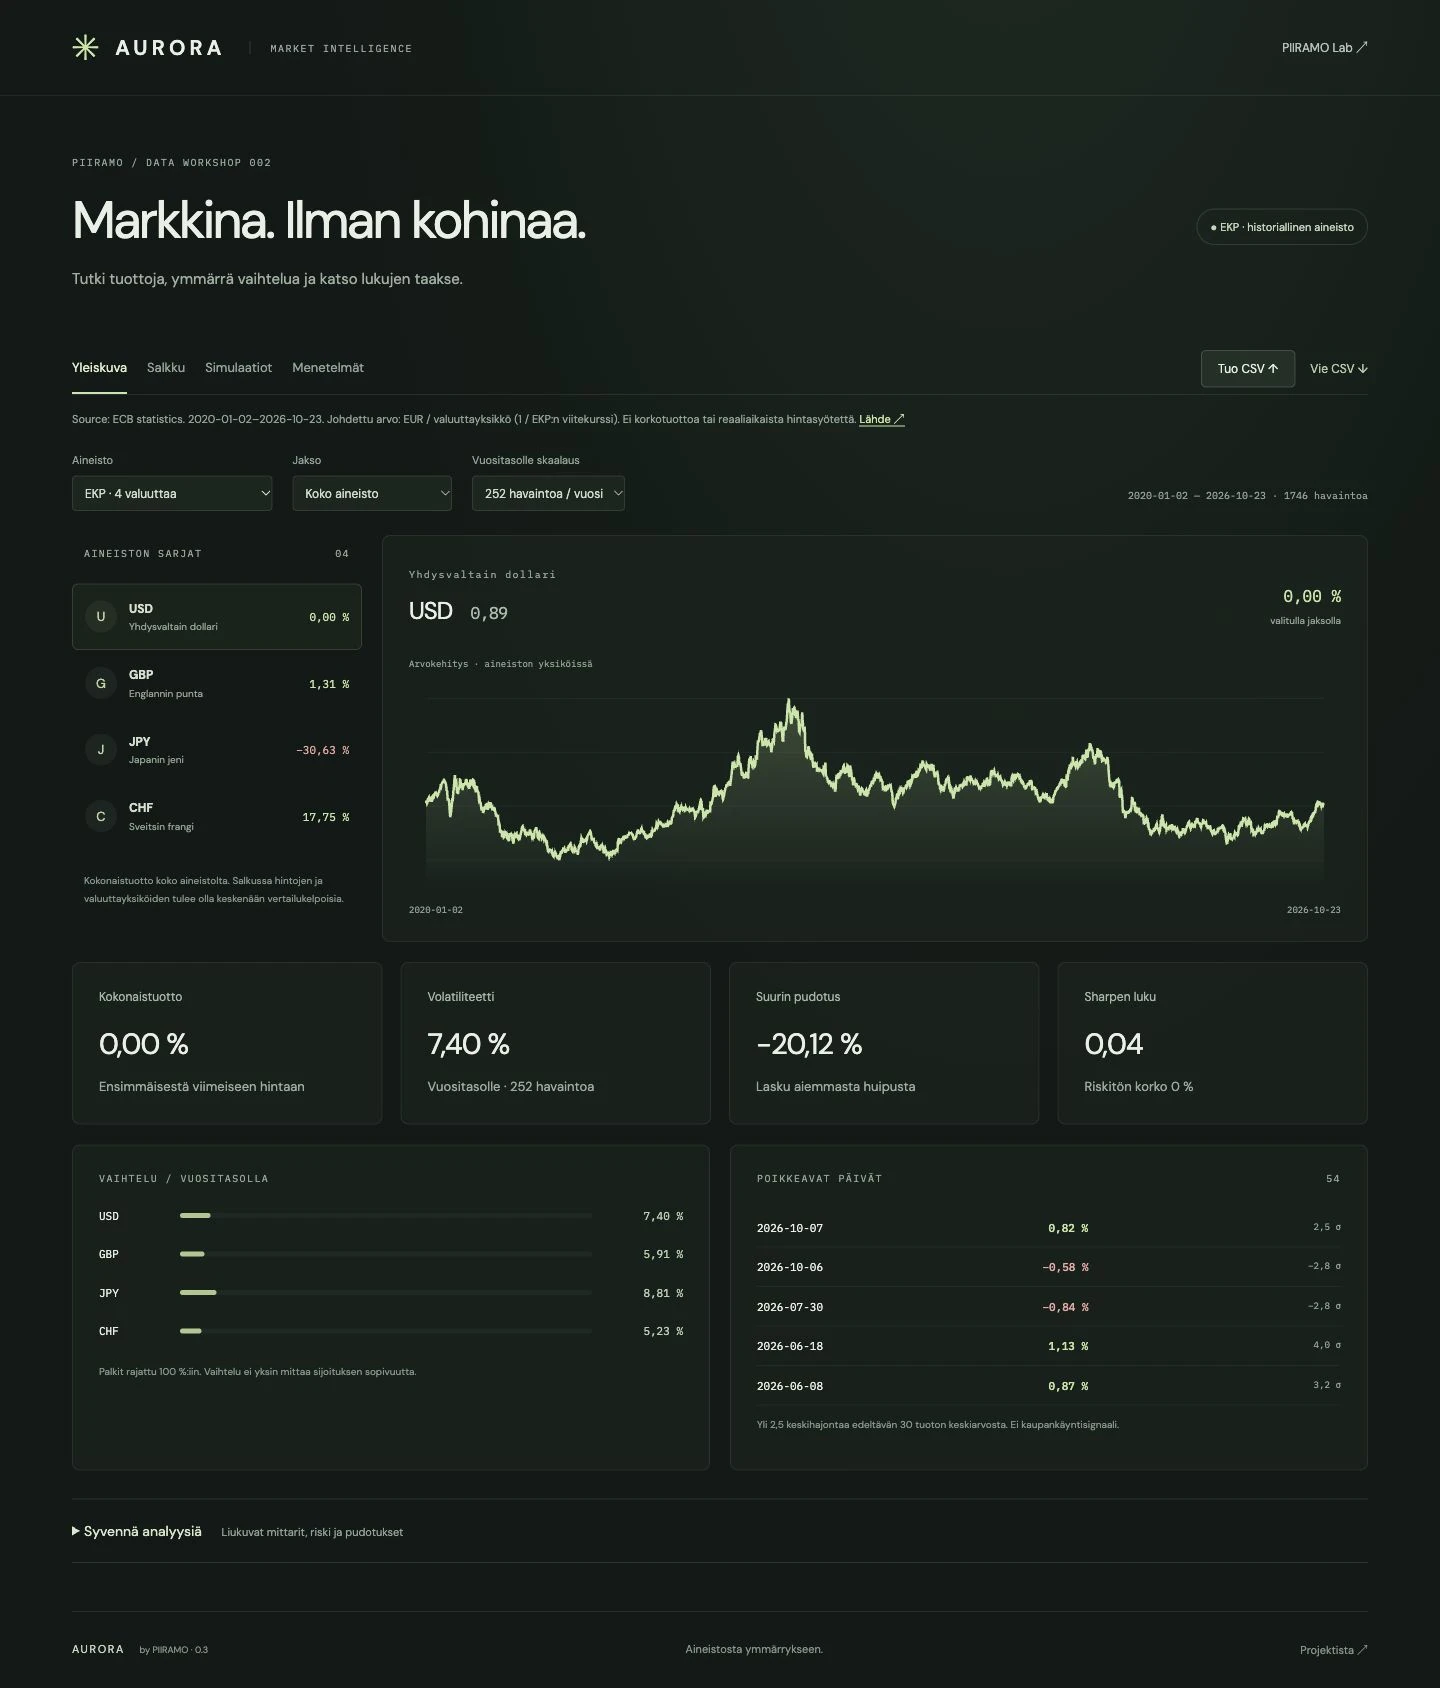
Browser version 0.4A market-data workshop with a built-in ECB dataset. Explore currencies, compare risk, optimise a portfolio and try Monte Carlo simulations. You can also bring your own CSV.
Open Aurora ↗ (opens in a new tab)No installation or account required.
Opens in a new tab. Demo interface: Finnish.
Opens in a new tab. Demo interface: Finnish.
The problem and the goal
How can raw data become a clear view of returns, variation and relationships between time series?
- Implementation
- We connected historical ECB data to a clear interface and made return, risk, optimisation and simulation tools available in the browser.
- The result so far
- The built-in dataset opens without installation or an account. Explore four currencies, build a model portfolio or import your own CSV. Risk calculations have been compared with a Python implementation, and minimum-variance weights with an exact SciPy reference.
What can you try?
- A guided research workflow, personal observations and JSON research reports
- Price chart with series and date-range selection
- CSV import and export, plus portfolio analysis as JSON
- Total return, volatility, Sharpe ratio and maximum drawdown
- Editable portfolio weights and a correlation matrix
- Anomaly detection, rolling averages, Sharpe ratios, volatility and correlation
- Historical and parametric VaR and Expected Shortfall
- Portfolio optimisation and an approximate efficient frontier
- Monte Carlo simulations, distributions and JSON export
Where next?
Improve data quality checks, currency and calendar handling, and continue work on an authenticated server version.
Browser analysis of your own dataset.
- The default dataset contains historical ECB exchange rates from 2 January 2020 to 23 October 2026. There is no continuous collection or live market feed. The alternative practice dataset is synthetic.
- CSV: one positive daily price per series, up to 12 series and 5,000 observation rows.
- Portfolios assume daily rebalancing and exclude fees, taxes, accrued interest and currency conversion costs.
- Optimisation and Monte Carlo run in the browser. The Python API and database are separate. Optimisation uses sampling approximations; simulations depend on model assumptions.
Your idea / The next improvement
What is missing?
Would you like a new feature, another tool or a simpler way to use the demo? Tell us what you have in mind.
No order. No commitment.Suggestion for: Aurora Market Intelligence
Suggest an improvement
Your suggestion arrives as a private message. Whether to implement it is decided separately.